Net Operating Income for Rental Property: How to Calculate NOI
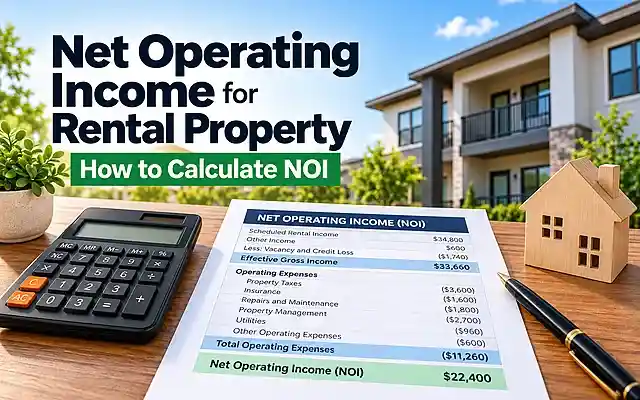
Net operating income for rental property measures what a rental property produces from operations after vacancy, credit loss, and recurring operating expenses are accounted for, but before investor financing under the property-level convention used in this guide.
The basic formula is NOI = Effective Gross Income – Operating Expenses
The arithmetic is simple. The more important work is deciding which income is supportable, which expenses belong above NOI, and whether the assumptions reflect how the property actually operates.
A rental property can show an attractive NOI on paper if rent is overstated, vacancy is ignored, or normal expenses are missing. That is why investors should rebuild the calculation from the underlying numbers rather than accept a listing or seller-provided NOI without review.
This guide explains how to calculate NOI, what belongs in the calculation, what is normally excluded, how to handle reserves and capital expenditures, and how NOI differs from cash flow, taxable rental income, and cap rate.
The examples are hypothetical and educational. Actual rents, vacancy, expenses, financing, taxes, and underwriting conventions vary by property and market.
What Net Operating Income Means for a Rental Property
Net operating income, usually shortened to NOI, is a property-level measure of operating performance.
It answers a specific question:
How much income does the property produce after its normal operating costs, but before the investor’s financing structure is applied?
That distinction matters because the same rental property can produce the same NOI for two investors while generating very different cash flow.
One investor might buy with cash. Another might use a highly leveraged loan. The property’s rents, vacancy, taxes, insurance, maintenance, and other operating costs do not automatically change because the buyers chose different financing.
Their financing cash requirements can be very different.
That is why the NOI convention used here keeps principal and interest below NOI and analyzes financing separately.
Fannie Mae’s current Multifamily Guide defines NOI as effective gross income minus operating expenses. Its Multifamily Analysis of Operations definitions also calculate NOI before the form’s later cash-flow and debt-service analysis.
NOI is therefore an important building block rather than a complete investment decision.
For the broader process that combines income, expenses, financing, returns, and stress testing, see Rental Property Analysis.
If the next question is how loan structure or leverage affects the investment, see Investment Property Financing.
Net Operating Income Formula
The short formula is NOI = Effective Gross Income – Operating Expenses
But an investor normally has to build effective gross income first.
A more complete rental-property waterfall is:
Scheduled Rental Income
+ Supportable Recurring Other Income
– Vacancy and Credit Loss
= Effective Gross Income
Then:
Effective Gross Income
– Recurring Operating Expenses
= Net Operating Income
This sequence prevents a common mistake: treating scheduled rent as though every unit will remain occupied and every dollar will be collected.
Fannie Mae’s current income-analysis framework separates potential rental income, vacancy or collection effects, other income, and operating expenses when developing effective gross income and underwritten property cash flow.
The exact line-item presentation can vary among investors, appraisers, lenders, and software platforms. The key is to state the convention and apply it consistently.
Step 1: Calculate Scheduled Rent and Other Property Income
Start with the rent the property can support. For an occupied property, distinguish between the rent tenants are contractually paying and a higher market rent that might be achievable later.
Suppose a tenant currently pays $1,800 per month but comparable properties suggest the unit might rent for $2,000 after the lease expires. Those are two different facts.
The $1,800 is current contractual rent. The $2,000 may be useful in a forward-looking analysis, but it should not automatically replace the current rent in an actual operating calculation.
The same principle applies to vacant units, planned renovations, lease renewals, and projected rent increases.
For deeper analysis of market rent, comparable properties, and local conditions, see Real Estate Market Analysis.
Other recurring property income
Rental properties can generate income beyond base rent.
Depending on the property, recurring operating income might include parking, laundry, storage, pet-related charges where lawful and supportable, utility reimbursements, or other property-specific sources.
Fannie Mae’s operating definitions recognize categories such as laundry, vending, parking, storage, pet income, and certain reimbursements in property operating analysis. Form 4254.DEF provides the line-item definitions.
The controlling question is whether the income is recurring, supportable, and connected to normal property operations.
A one-time windfall should not be treated like dependable annual operating income.
Refundable security deposits also require care. A deposit expected to be returned to the tenant is not ordinary rental income merely because the owner temporarily holds the cash. IRS Publication 527 likewise distinguishes refundable security deposits from amounts that become income because the owner is entitled to retain them.
Step 2: Account for Vacancy and Credit Loss
Scheduled rent assumes full occupancy and full collection. Real properties rarely operate under that assumption forever.
Units can sit vacant between tenants. Tenants can leave unexpectedly. Rent can go uncollected. Concessions may reduce the amount actually realized.
That gap is why an NOI model should account for vacancy and credit loss before calculating effective gross income.
There is no universal vacancy percentage that belongs in every rental-property analysis.
A supportable assumption can depend on the property’s history, lease expirations, tenant profile, local vacancy conditions, unit type, location, and current competition.
Current OCC commercial real estate lending guidance notes that NOI analysis may use stabilized vacancy and expense assumptions rather than simply copying actual cash-basis results.
That is commercial-lending guidance, not a mandatory rule for a small residential investor. The useful principle is that the assumption should be supportable and clearly stated.
If an example uses 5%, state that 5% is an example. Do not present it as a national rule.
Step 3: Subtract Rental Property Operating Expenses
Once effective gross income is established, subtract the recurring expenses required to operate and maintain the property.
Typical categories can include property taxes, property insurance, routine repairs and maintenance, property management, owner-paid utilities, landscaping, pest control, HOA or condominium charges, licensing, and other recurring property-specific costs.
Not every property will have every expense.
A single-family rental with tenant-paid utilities may have a different expense structure from a small multifamily building with common-area electricity, water, trash collection, landscaping, and professional management.
The goal is not to force every property into the same expense ratio. The goal is to capture the property’s real operating economics consistently.
Fannie Mae’s income-analysis guidance uses line-by-line stabilized operating expenses and specifically includes categories such as management and insurance, while the related Form 4254 definitions include taxes, utilities, repairs and maintenance, and other operating lines.
What if you manage the property yourself?
A self-managing investor may not write a monthly check to a third-party property manager. That does not necessarily mean management has zero economic cost.
If you are comparing properties or evaluating whether the investment still works if professional management becomes necessary, it can be useful to model a supportable management expense.
Fannie Mae’s Form 4254 distinguishes borrower-reported figures from normalized figures in property operating analysis. That lender-specific framework should not be copied mechanically into a small rental-property model, but the underlying analytical point is useful: the current owner’s cash payment is not always the only relevant way to test an operating function.
What Is Included and Excluded From NOI?
The following table uses the property-level convention applied throughout this guide.
| Item | NOI treatment | Why |
|---|---|---|
| Rental income | Included | Core operating income |
| Recurring parking, laundry, storage, or similar income | Included when supportable | Normal property operations |
| Vacancy and credit loss | Reduces income | Converts scheduled income toward effective gross income |
| Property taxes | Operating expense | Recurring cost of property operations |
| Property insurance | Operating expense | Recurring property-level cost |
| Routine repairs and maintenance | Operating expense | Normal upkeep |
| Property management | Operating expense | Cost of operating the rental |
| Owner-paid utilities | Operating expense | Recurring property cost |
| HOA or condominium charges | Usually an operating expense when applicable | Recurring ownership or operating cost |
| Mortgage principal | Excluded | Financing, not property operations |
| Mortgage interest | Excluded from this NOI convention | Financing cost |
| Investor income taxes | Excluded | Investor-specific tax result |
| Depreciation | Excluded | Noncash tax or accounting deduction, not a current property operating cash expense |
| Acquisition closing costs | Excluded | Transaction cost rather than recurring operations |
| Appreciation | Excluded | Change in asset value, not operating income |
| Capital expenditures | Modeled separately under this guide’s convention | Long-lived asset expenditure rather than routine operations |
| Replacement reserve | Modeled below NOI in this guide | Convention-sensitive allowance for future capital needs |
The treatment of financing deserves special emphasis.
Fannie Mae’s Form 4254 excludes mortgage interest expense and principal payments from its operating-expense calculation, computes NOI, and addresses debt service later in the cash-flow section. The same form calculates net cash flow after capital expenditures by subtracting its replacement-reserve line from NOI.
That structure is also why NOI and cash flow should not be used interchangeably.
Replacement Reserves and Capital Expenditures Need a Stated Convention
Replacement reserves and capital expenditures are among the easiest areas for two analysts to produce different NOI figures from similar property facts.
Under the convention used in this guide, NOI is calculated before a separately modeled replacement reserve.
Fannie Mae’s Form 4254.DEF provides a current example of this structure. It calculates NOI as effective gross income minus total operating expenses, places replacement-reserve or capital-expenditure items in a separate section, and subtracts the replacement-reserve amount from NOI when calculating net cash flow.
Other underwriting frameworks can treat reserves differently. Current OCC guidance, for example, notes that NOI analysis may incorporate replacement reserves when developing a stabilized estimate of property income and expenses.
That difference does not mean one NOI is automatically correct and the other is wrong. It means you need to know the convention before comparing two numbers.
If one investor reports NOI before reserves and another reports NOI after a replacement allowance, their results can differ even when the underlying property assumptions are otherwise similar.
Capital expenditures also should not be confused with routine maintenance.
Routine repairs may belong in operating expenses, while replacement of major systems or improvements with a multi-year useful life may be treated separately as capital expenditures.
The practical rule is consistency. Do not subtract an estimated replacement reserve and then also deduct the same expected capital need again elsewhere without recognizing the duplication.
Worked Example: Calculate NOI for a Rental Property
Consider a hypothetical rental property with the following assumptions.
| Input | Hypothetical assumption |
|---|---|
| Monthly scheduled rent | $2,900 |
| Scheduled annual rent | $34,800 |
| Other recurring income | $600 per year |
| Vacancy and credit loss | 5% of scheduled annual rent |
| Effective gross income | $33,660 per year |
| Property taxes | $3,600 per year |
| Insurance | $1,600 per year |
| Routine maintenance | $1,800 per year |
| Property management | $2,700 per year |
| Owner-paid utilities | $960 per year |
| Licensing / recurring administration | $600 per year |
| Total operating expenses | $11,260 per year |
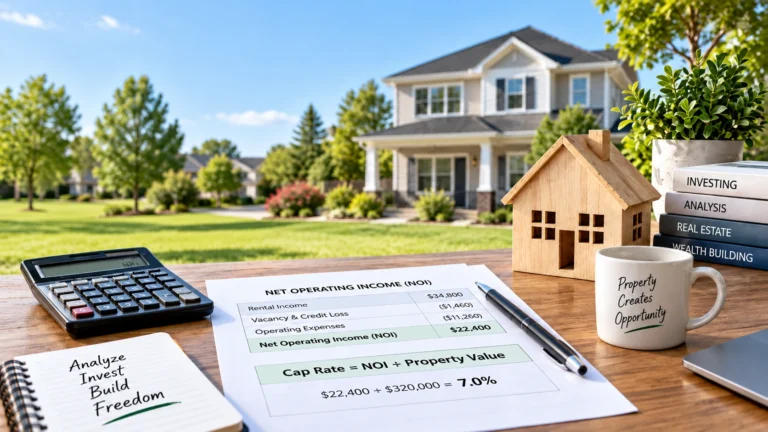
| Net operating income | $22,400 per year |
The 5% vacancy assumption is used only to demonstrate the calculation. It is not a recommended vacancy rate.
Calculate scheduled annual rent
$2,900 x 12 = $34,800
Calculate vacancy and credit loss
$34,800 x 5% = $1,740
Calculate effective gross income
$34,800 scheduled rent
+ $600 other recurring income
– $1,740 vacancy and credit loss
= $33,660 effective gross income
Subtract operating expenses
Total recurring operating expenses are $11,260.
Therefore:
NOI = $33,660 – $11,260
NOI = $22,400
The property’s hypothetical annual NOI is $22,400 under the stated assumptions and convention.
Notice what has not yet been deducted: mortgage payments.
If the investor later finances the property, debt service affects cash flow, not the $22,400 property-level NOI calculated here.
For that next calculation, see Rental Property Cash Flow.
Actual NOI vs. Pro Forma vs. Stabilized NOI
Not every NOI figure describes the same time period or set of assumptions.
Actual or trailing NOI
Actual NOI is built from the property’s historical operating results.
An investor might review the prior calendar year or a trailing 12-month operating statement and reconstruct NOI from actual rents, vacancy, collections, and expenses.
Historical performance is useful because it shows what the property has actually produced, but the figures still need review. A repair spike, unusual vacancy period, unpaid expense, or missing management cost can distort one period.
Pro forma NOI
Pro forma NOI is forward-looking.
It estimates what the property could produce under a set of future assumptions.
Those assumptions might include lease renewals, market rents, higher occupancy, revised taxes, new insurance costs, planned renovations, or professional management.
A pro forma can be useful, but the assumptions should be treated as assumptions.
Current OCC underwriting guidance emphasizes reviewing whether projected income and expenses are reasonable and supported by operating history, market evidence, contracts, budgets, and comparable properties.
If a seller’s offering memorandum shows an NOI based on rents that have not yet been achieved, that figure should not be treated as established historical income.
Stabilized or underwritten NOI
Stabilized NOI attempts to represent a sustainable operating level rather than simply copying one historical period.
An analyst might normalize vacancy, management, repairs, or other expenses when recent results are unusually high or low.
Fannie Mae’s operating analysis distinguishes borrower actual figures from normalized figures, and current OCC guidance likewise describes the underwriting objective of developing a stabilized estimate of income and expenses.
The important point is labeling. Do not compare actual NOI, seller pro forma NOI, and normalized underwriting NOI as though they are identical measurements.
NOI vs. Cash Flow, Taxable Rental Income, and Cap Rate
NOI sits inside a larger financial framework, but it should not be confused with the metrics that come after it.
| Measure | Basic question | Key distinction |
|---|---|---|
| NOI | What does the property produce from operations? | Before financing under this guide’s convention |
| Cash flow | What cash remains after financing and defined below-NOI requirements? | Financing-sensitive |
| Taxable rental income or loss | What result is calculated under applicable tax rules? | Uses tax-law deductions and accounting rules |
| Cap rate | How does NOI relate to property price or value? | Property-level valuation relationship |
NOI vs. cash flow
A property can have positive NOI and negative investor cash flow.
For example, the property may produce $22,400 of NOI but have debt service and other below-NOI cash requirements that exceed that amount.
That does not make the NOI calculation wrong. It means NOI and cash flow answer different questions.
NOI vs. taxable rental income
Tax reporting follows tax law, not an investment-underwriting NOI formula.
IRS Publication 527 lists mortgage interest and depreciation among common rental-property tax deductions and explains tax treatment for repairs, improvements, and other rental expenses.
Those tax categories do not automatically become NOI operating expenses.
This is why an investor should not copy Schedule E categories directly into an NOI calculation and assume the result represents property-level operating income.
For tax decisions, use the applicable IRS guidance and a qualified tax professional where appropriate.
NOI vs. cap rate
Cap rate connects NOI to the property’s price or value:
Cap Rate = Annual NOI / Property Price or Value x 100
The Federal Reserve Bank of San Francisco describes the capitalization rate as the ratio of net operating income to property price in commercial real estate.
Using the hypothetical $22,400 NOI from this article and a $320,000 property price would produce a 7.0% cap rate.
That calculation belongs to the next analytical step. For the complete treatment of price, value, cap-rate interpretation, and comparison errors, see Rental Property Cap Rate.
What Is a Good NOI for a Rental Property?
There is no universal dollar amount that makes an NOI good.
A $20,000 NOI could be substantial for one property and inadequate for another.
Property scale alone makes a universal dollar threshold impractical. A duplex, a 20-unit building, and a 200-unit apartment property should not be expected to produce the same NOI.
A useful evaluation starts by asking whether the NOI itself is supportable.
Are the rents real? Is vacancy accounted for? Are expenses complete? Does the result depend on aggressive future assumptions? Is the property currently stabilized? Are insurance and taxes based on realistic costs?
Then place the NOI in context.
An investor may use NOI to calculate cap rate, evaluate changes in property operations, test downside scenarios, or determine whether the asset produces enough operating income to support later stages of underwriting.
Lenders can also use NOI or related cash-flow measures in debt-coverage analysis, but the exact numerator and underwriting adjustments vary by program. That is why a debt-service coverage ratio (DSCR) calculation should follow the applicable lender’s rules rather than assume every lender uses the same NOI definition.
A larger NOI is not automatically proof of a better investment.
A property may have a larger NOI because it has more units, higher effective gross income, or lower operating expenses. Price alone does not create NOI, and the NOI figure still does not reveal the property’s capital needs, financing terms, market risk, or investor return.
NOI is an important measurement, not an investment verdict.
Common Rental Property NOI Mistakes
| Mistake | Why it causes problems |
|---|---|
| Using scheduled rent as NOI | Ignores vacancy and operating expenses |
| Assuming full collection | Can overstate effective gross income |
| Omitting normal expenses | Makes NOI look stronger than the property economics |
| Including mortgage payments in NOI | Mixes property operations with investor financing |
| Treating depreciation as an NOI operating expense | Confuses tax accounting with current property operations |
| Treating all capital spending as routine maintenance | Blurs recurring operations and long-lived asset investment |
| Using reserves inconsistently | Makes NOI comparisons unreliable |
| Double counting vacancy or expenses | Artificially depresses the result |
| Mixing monthly income with annual expenses | Produces an inconsistent calculation |
| Accepting listing NOI without rebuilding it | Leaves the seller’s assumptions untested |
| Treating pro forma rent as established income | Converts a forecast into an apparent historical fact |
| Assuming positive NOI means positive cash flow | Ignores financing and other below-NOI requirements |
One of the most useful habits is to rebuild the NOI yourself.
Ask what changed between the seller’s calculation and yours.
A difference does not automatically mean the seller is wrong. It may come from different vacancy assumptions, property-tax estimates, insurance costs, management treatment, reserve conventions, or definitions of recurring expenses.
The task is to reconcile the assumptions.
Rental Property NOI Checklist
Before relying on an NOI figure, confirm the following:
| Area | Check |
|---|---|
| Rent | Verify current contractual rent and distinguish it from market or projected rent |
| Other income | Include only supportable recurring property income |
| Vacancy | Apply a clearly stated, supportable vacancy and credit-loss assumption |
| Taxes | Use a realistic property-tax assumption |
| Insurance | Use a supportable current or projected premium |
| Maintenance | Include normal recurring repairs and upkeep |
| Management | Decide whether a normalized management expense is appropriate |
| Utilities | Include owner-paid recurring utilities |
| Other expenses | Capture property-specific recurring costs |
| Reserves | State whether replacement reserves are above or below the reported NOI |
| Capital expenditures | Keep capital-spending treatment separate and avoid double counting |
| Financing | Keep mortgage principal and interest outside NOI under this convention |
| Time period | Use consistent monthly or annual periods |
| Pro forma | Label forward-looking assumptions clearly |
| Final NOI | Recalculate the arithmetic and compare it with historical results |
Once the NOI is supportable, move into the rest of the underwriting process rather than treating the number as a stand-alone decision.
For the broader metric and underwriting framework, see Real Estate Deal Analysis.
Frequently Asked Questions
What is NOI on a rental property?
NOI is the income produced by the rental property’s operations after effective gross income is reduced by recurring operating expenses. Under the convention used here, financing is excluded.
How do you calculate net operating income for rental property?
First calculate effective gross income by taking scheduled rental income, adding supportable recurring other income, and subtracting vacancy and credit loss. Then subtract recurring operating expenses.
NOI = Effective Gross Income – Operating Expenses
Does NOI include the mortgage?
No, not under the property-level convention used in this guide. Mortgage principal and interest belong to financing and affect investor cash flow rather than property operating income.
Does NOI include property taxes?
Yes. Property taxes are normally treated as a recurring property operating expense.
Does NOI include insurance?
Yes. Property insurance is normally an operating expense.
Does NOI include repairs and maintenance?
Routine repairs and maintenance normally belong in operating expenses. Major replacements or improvements with longer useful lives may require separate capital-expenditure treatment.
Does NOI include property management?
Property-management expense generally belongs in operating expenses. Investors who self-manage may still choose to model a supportable management cost when comparing properties or normalizing operations.
Does NOI include vacancy?
Vacancy affects NOI by reducing the income available before operating expenses. It is normally reflected when converting scheduled or potential rent into effective gross income.
Does NOI include capital expenditures?
Under the convention used in this guide, capital expenditures are modeled separately rather than included in recurring operating expenses.
Does NOI include replacement reserves?
This guide calculates conventional NOI before a separately modeled replacement reserve. Other underwriting frameworks can use a different convention, so identify the treatment before comparing NOI figures.
Does NOI include depreciation?
No. Depreciation is a tax and accounting concept rather than a current property operating cash expense in this NOI model.
Does NOI include income taxes?
Investor income taxes are excluded from the property-level NOI calculation used here.
Can NOI be negative?
Yes. If effective gross income is lower than the property’s operating expenses, NOI can be negative.
That is an underwriting warning because the property is not covering its operating costs before financing.
Is NOI calculated monthly or annually?
You can calculate NOI for different periods if the income and expense periods are consistent. Investors commonly use annual NOI when calculating cap rate or comparing annual property performance.
What is a good NOI for a rental property?
There is no universal good NOI dollar amount. Evaluate whether the income and expense assumptions are supportable, how the NOI changes over time, how it relates to the property’s price or value, and whether the broader investment still works after financing and risk are considered.
What is the difference between NOI and cash flow?
NOI measures property operating income before financing under the convention used here. Cash flow measures what remains after financing and other defined below-NOI cash requirements.
What is the difference between NOI and taxable rental income?
NOI is an investment and property-underwriting measure. Taxable rental income or loss follows tax rules and can include deductions such as mortgage interest and depreciation that are not operating expenses in this NOI model.
Use NOI as the Starting Point, Not the Final Answer
A reliable NOI starts with realistic income, a visible vacancy assumption, complete operating expenses, and a clearly stated treatment of reserves and capital expenditures.
The formula itself is easy:
NOI = Effective Gross Income – Operating Expenses
The value of the calculation comes from the assumptions behind it.
Once you have rebuilt the property’s NOI and are comfortable with the inputs, the next question is what that income means relative to the property’s price or value. Continue with Rental Property Cap Rate.
If you are evaluating the entire acquisition rather than one metric, return to Rental Property Analysis for the complete underwriting process.