Cash-on-Cash Return: How to Calculate It for Rental Property
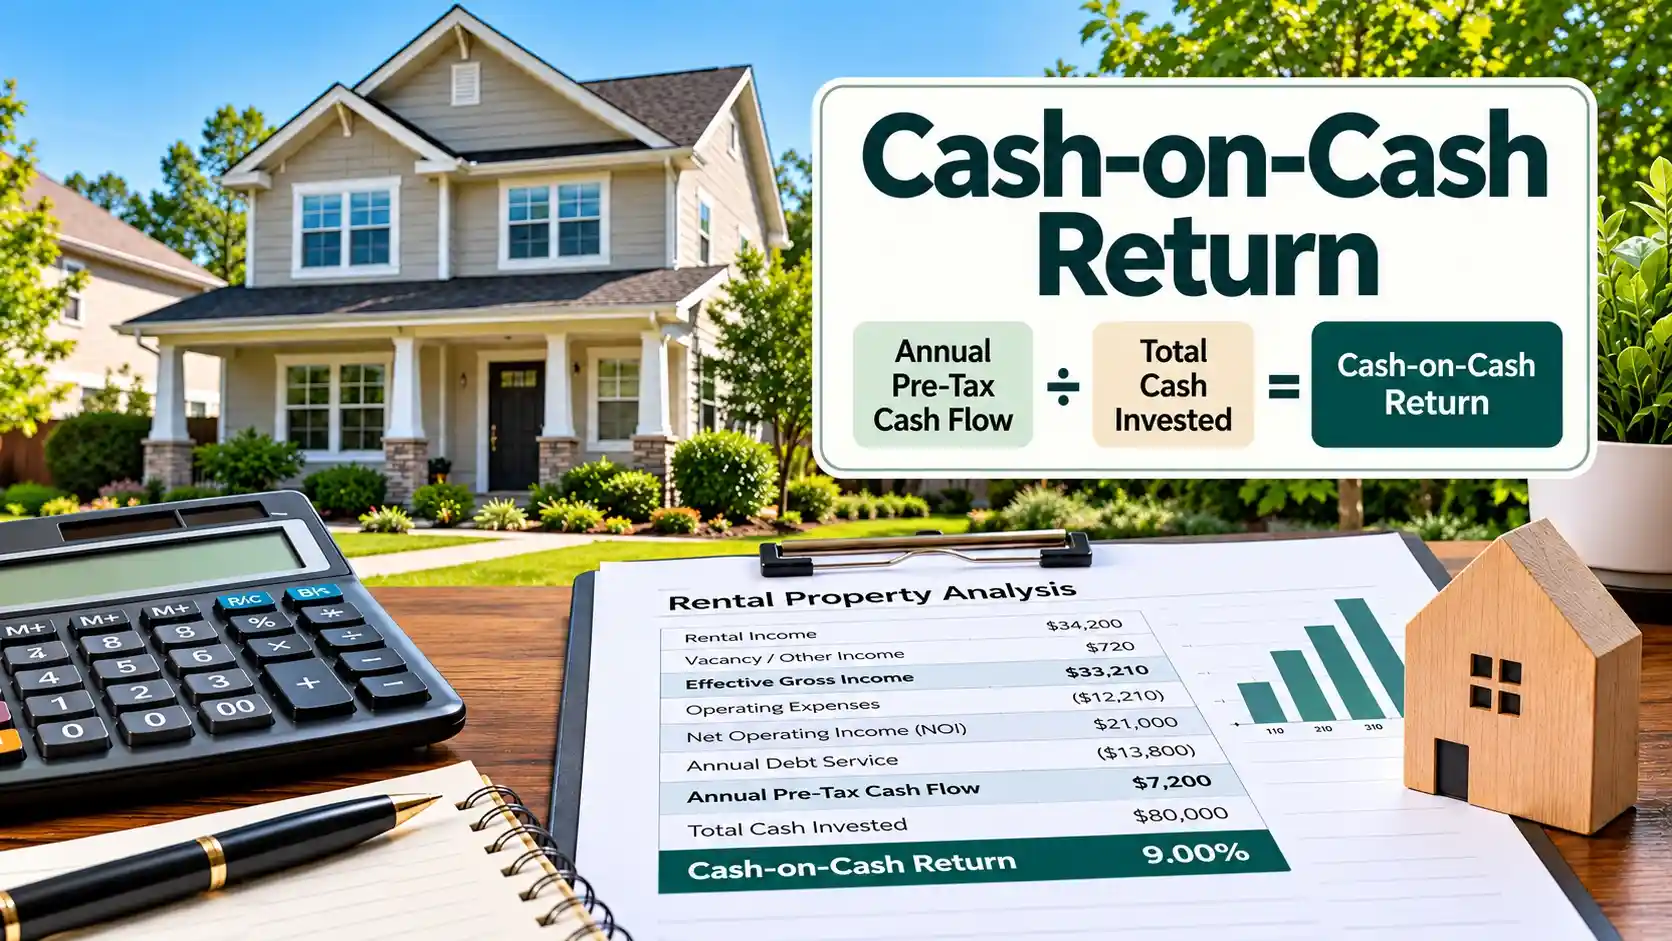
Cash on cash return shows how much annual pre-tax cash flow a real estate investment produces relative to the investor cash committed to the deal. For a financed rental property, it is an investor-level, financing-sensitive metric rather than a property-level measure of operating performance.
The formula is: Cash-on-Cash Return = Annual Pre-Tax Cash Flow / Total Cash Invested × 100
An accurate result depends on more than the final division. The numerator must reflect a supportable cash-flow convention, while the denominator must capture the investor cash included in the analysis. Omitting debt service, acquisition cash, or required initial work can materially distort the percentage.
This guide focuses on acquisition-stage rental-property underwriting and explains how to build both sides of the calculation, how financing changes the result, and how to interpret the percentage without treating it as a stand-alone investment verdict. For the complete acquisition workflow, see Rental Property Analysis.
Important: The examples in this guide are hypothetical and educational. They do not represent current mortgage terms, market rents, expense ratios, or recommended investment returns. Verify material assumptions for the specific property, financing, and market you are evaluating.
What Is Cash-on-Cash Return?
Cash-on-cash return, often shortened to CoC return, answers a practical investor-level question: how much annual pre-tax cash flow is the property producing relative to the cash you actually have invested?
J.P. Morgan’s explanation of cash-on-cash return describes the metric as annual cash flow divided by total cash invested and notes that it is typically calculated using pre-tax annual cash flow.
Suppose two rental properties each produce $8,000 of annual pre-tax cash flow. If one requires $80,000 of investor cash and the other requires $120,000, the dollar cash flow is identical but the cash-on-cash return is not.
For the first property: $8,000 / $80,000 × 100 = 10%
For the second: $8,000 / $120,000 × 100 = 6.67%
The percentage adds information that the dollar cash-flow figure alone does not provide. It shows how the annual cash flow relates to the amount of investor capital committed.
That does not make the higher percentage automatically better. The two properties may have different financing, physical condition, future capital needs, locations, income stability, or risk. Cash-on-cash return organizes one part of the analysis. It does not settle the entire investment decision.
For the underlying dollar calculation, see Rental Property Cash Flow.
Cash-on-Cash Return Formula
For an acquisition-focused rental-property analysis, use:
Cash-on-Cash Return = Annual Pre-Tax Cash Flow / Total Cash Invested × 100
The formula has two parts that need to be defined clearly.
The numerator: annual pre-tax cash flow
A common starting convention for a financed property is:
Annual Pre-Tax Cash Flow = Net Operating Income – Annual Debt Service
Net operating income, or NOI, measures property-level income after normal operating expenses but before investor financing under the convention used by Realty Crafts. Debt service then brings the financing layer into the calculation.
If you need to build NOI from the property records, rents, vacancy, and expenses, use the dedicated guide to net operating income for rental property.
Some underwriting models also deduct separately modeled reserves or other defined cash requirements below NOI. In that case, the numerator can be expressed more specifically as:
Pre-Tax Modeled Cash Flow = NOI – Debt Service – Separately Modeled Below-NOI Cash Requirements
The important control is consistency. If a capital reserve is already included in the operating-expense convention used to calculate NOI, do not subtract it again below NOI. If it is excluded from NOI and modeled separately, label that treatment clearly.
Two analysts can calculate different cash-on-cash returns for the same property if they use materially different cash-flow conventions. Before comparing the percentages, compare what each numerator actually includes.
The denominator: total cash invested
For a rental property being acquired with financing, total cash invested generally starts with the investor’s actual cash required to acquire the property and place it into the condition assumed by the underwriting.
That can include the down payment, buyer-paid closing costs, financing costs paid in cash, and immediate repairs or improvements required to make the property ready for its intended use. J.P. Morgan specifically identifies items such as down payment, closing costs, and initial improvements as possible components of cash invested.
The denominator should reflect the economic question you are asking. Leaving out a material upfront cash requirement can make the cash-on-cash return look stronger than the investment actually is.
How to Calculate Cash-on-Cash Return Step by Step
A reliable cash-on-cash calculation starts before the final division. Build the property economics first, then add financing, then identify the investor cash committed.
Step 1: Estimate effective rental income
Start with supportable scheduled rent and any recurring property income that is reasonably expected. Then account for vacancy and credit loss rather than assuming every scheduled dollar will be collected.
The purpose is not to force a universal vacancy percentage into every deal. Use property history, lease terms, comparable rentals, and local market evidence that fit the property being analyzed.
Step 2: Subtract normal operating expenses
Operating expenses can include property taxes, insurance, routine maintenance, management, owner-paid utilities, association costs where applicable, recurring licensing or administrative expenses, and other normal costs required to operate the property.
Expense classification matters because missing expenses can inflate NOI and everything calculated from it. For a line-by-line framework, see Rental Property Expenses.
Step 3: Calculate NOI
Under the Realty Crafts property-level convention: NOI = Effective Gross Income – Operating Expenses
Mortgage principal and interest are not operating expenses in this NOI calculation. They enter when you move from property-level NOI to investor-level cash flow.
Step 4: Subtract annual debt service
For a standard fully amortizing mortgage, principal and interest are part of annual debt service. Other loan structures can produce different debt-service patterns, so use the actual scheduled debt service that matches the financing terms being analyzed.
Subtract that annual debt service from NOI to reach the common pre-tax cash-flow starting point.
Be careful when reviewing mortgage statements or seller calculations that combine principal, interest, taxes, and insurance into one monthly payment. If property taxes and insurance are already included as operating expenses above NOI, subtracting the entire combined payment again can count those expenses twice.
Step 5: Account for separately modeled cash requirements
If your underwriting model subtracts a capital reserve or another defined cash requirement below NOI, apply it once and label it.
This step is especially important when comparing your calculation with a lender, broker, software platform, or another investor. A percentage is not fully comparable until you understand the underlying cash-flow convention.
Step 6: Calculate total cash invested
Add the investor cash required for the acquisition under the convention you are using. For a straightforward purchase, that may include the down payment, buyer-paid closing costs, cash-paid financing costs, and immediate rent-ready work.
Do not automatically use the full property price as the denominator when the question is cash-on-cash return for a financed acquisition. The metric is designed to relate annual cash flow to investor cash or equity, not to the property’s entire purchase price.
Step 7: Divide annual pre-tax cash flow by total cash invested
Once both figures are established:
Annual Pre-Tax Cash Flow / Total Cash Invested = Cash-on-Cash Return
Multiply the decimal result by 100 to express it as a percentage.
What Counts as Cash Invested?
The denominator deserves as much attention as the numerator because an incomplete denominator can materially overstate the return.
For an acquisition-focused rental-property calculation, common components can include:
- the down payment;
- buyer-paid closing costs;
- loan points or other financing costs paid in cash where applicable;
- immediate repairs or improvements needed to place the property into the assumed operating condition; and
- other required upfront investor contributions that are genuinely part of the acquisition economics.
For a financed purchase, total cash invested can include the down payment, buyer-paid closing costs, and immediate rent-ready work. The worked example below identifies those amounts and adds them together, rather than treating the down payment alone as the investor’s entire cash commitment.
Not every investment situation is this simple. Analysts can differ in how they handle restricted reserves, later capital contributions, refinances, and additional equity invested after acquisition. Adventures in CRE uses a convention based on total equity contributions to date, which illustrates why ongoing investment analysis can require a different denominator from a simple acquisition-day calculation.
Required reserves and retained liquidity also need careful labeling. Cash that a lender requires an investor to keep available after closing is not necessarily the same as cash spent on the acquisition. If those funds are included in the cash-on-cash denominator, state that convention explicitly rather than treating every dollar associated with closing as though it were consumed by the transaction.
For Realty Crafts’ acquisition example, the denominator is the upfront investor cash required to acquire and prepare the property. If later equity contributions or retained reserve requirements are being analyzed, state the time period and denominator convention rather than silently mixing them with the original acquisition calculation.
Worked Example: Cash-on-Cash Return for a Rental Property
The following example is hypothetical. It is designed to show the calculation process, not to represent current market rents, financing terms, expense ratios, or a target return.
| Item | Hypothetical annual or acquisition amount |
|---|---|
| Purchase price | $260,000 |
| Monthly scheduled rent | $2,850 |
| Scheduled annual rent | $34,200 |
| Other recurring income | $720 |
| Vacancy and credit loss | $1,710 |
| Effective gross income | $33,210 |
| Operating expenses | $12,210 |
| NOI | $21,000 |
| Annual principal-and-interest debt service | $13,800 |
| Annual pre-tax cash flow | $7,200 |
| Down payment | $65,000 |
| Buyer-paid closing costs | $7,000 |
| Immediate rent-ready work | $8,000 |
| Total cash invested | $80,000 |
Step 1: Calculate effective gross income
Scheduled annual rent: $2,850 × 12 = $34,200
Add $720 of hypothetical recurring income and subtract $1,710 of hypothetical vacancy and credit loss:
$34,200 + $720 – $1,710 = $33,210 effective gross income
Step 2: Calculate NOI
Assume $12,210 in hypothetical annual operating expenses: $3,600 in property taxes, $1,800 in property insurance, $2,400 in routine maintenance, $2,700 in property management, $960 in owner-paid utilities, and $750 in recurring administration and licensing. These amounts total $12,210. The optional $1,200 annual capital reserve illustrated later is not included in this operating-expense subtotal.
$33,210 – $12,210 = $21,000 NOI
Step 3: Calculate annual pre-tax cash flow
Assume annual principal-and-interest debt service of $13,800 for the hypothetical fully amortizing loan used in this example.
$21,000 – $13,800 = $7,200 annual pre-tax cash flow
Step 4: Calculate total cash invested
$65,000 down payment + $7,000 closing costs + $8,000 immediate work = $80,000 total cash invested
Step 5: Calculate cash-on-cash return
$7,200 / $80,000 = 0.09
0.09 × 100 = 9.00% cash-on-cash return
Under the stated assumptions and convention, the hypothetical property produces a 9.00% cash-on-cash return.
Now suppose the investor also models a $1,200 annual capital reserve below NOI rather than including it in operating expenses. The modeled cash flow becomes:
$7,200 – $1,200 = $6,000
Using the same $80,000 denominator:
$6,000 / $80,000 × 100 = 7.50%
Neither percentage is useful without knowing the convention. The difference does not come from arithmetic. It comes from what the cash-flow numerator includes.
How Financing Changes Cash-on-Cash Return
Cash-on-cash return is financing-sensitive. A different loan structure can change both the amount of investor cash required and the annual debt service deducted from NOI.
Consider the same hypothetical property with $21,000 of NOI. One financing structure requires $80,000 of total investor cash and $13,800 of annual debt service. Another hypothetical structure requires only $54,000 of total investor cash but increases annual debt service to $15,600.
| Financing assumption | Total cash invested | Annual debt service | Annual pre-tax cash flow | Cash-on-cash return |
|---|---|---|---|---|
| Structure A | $80,000 | $13,800 | $7,200 | 9.00% |
| Structure B | $54,000 | $15,600 | $5,400 | 10.00% |
Structure B produces a higher cash-on-cash percentage even though it produces less annual dollar cash flow. The smaller denominator more than offsets the additional debt service in this hypothetical example.
That does not establish that Structure B is better. It uses more leverage and leaves less annual cash flow. Financing also affects required reserves, qualification, liquidity, default risk, refinancing exposure, and the investor’s ability to absorb an operating shortfall.
A higher cash-on-cash return created by additional leverage should therefore be interpreted together with the financing risk that helped create it. For the broader financing decision, see Investment Property Financing.
Cash-on-Cash Return vs. Cap Rate
Cash-on-cash return and cap rate both express a relationship as a percentage, but they answer different questions.
| Metric | Cash-on-Cash Return | Cap Rate |
|---|---|---|
| Numerator | Annual pre-tax investor cash flow | Annual NOI |
| Denominator | Investor cash invested | Property price or value |
| Financing effect | Financing affects the calculation | Financing is excluded under the property-level convention |
| Main question | How much current cash flow is produced relative to investor cash? | How much property-level NOI is produced relative to price or value? |
A property can have the same cap rate for two buyers while producing different cash-on-cash returns because the buyers use different financing structures or contribute different amounts of cash.
For a detailed explanation of the property-level metric, see Rental Property Cap Rate.
The two metrics should not be substituted for each other. Cap rate helps analyze property income relative to price or value. Cash-on-cash return brings the investor’s financing and invested cash into the analysis.
What Is a Good Cash-on-Cash Return?
There is no universal cash-on-cash return that automatically makes a rental property a good investment.
A published benchmark should not be treated as universal. Wall Street Prep explicitly notes that there is not necessarily one universally good cash yield and that market conditions, property type, and location affect interpretation. The percentage still has to be read in the context of the property, financing, assumptions, and risk behind it.
A cash-on-cash return should be evaluated in context. Relevant considerations include whether the rent is supportable, whether vacancy and operating expenses are complete, the condition of the property, expected near-term capital needs, the amount and structure of debt, liquidity, local market conditions, the reliability of the income stream, and the investor’s own objectives and constraints.
A 10% cash-on-cash return means annual pre-tax cash flow equals 10% of the investor cash included in the denominator under the stated convention. It does not mean the investment earned a 10% total return after appreciation, principal paydown, taxes, or eventual sale proceeds.
A 10% cash-on-cash return built on overstated rent or missing expenses is not stronger merely because the percentage is in double digits. A high result created by aggressive leverage can also come with thinner dollar cash flow and greater financing exposure.
Likewise, a 6% cash-on-cash return is not automatically poor. The meaning depends on what produced the number, the risks being taken, the capital tied up, and how the property compares with realistic alternatives available to that investor.
The useful question is not, “Is this percentage universally good?” It is, “Does this return accurately reflect the property’s supported cash flow and invested cash, and is the result appropriate for the risks and objectives being evaluated?”
What Cash-on-Cash Return Does Not Tell You
Cash-on-cash return is primarily a current cash-income measure. It does not by itself capture the full economic result of owning real estate over multiple years.
J.P. Morgan notes limitations that include changes in income and expenses over time, future capital investment, equity growth from loan paydown, appreciation, and eventual sale cash flow. Those omissions matter because a property can generate one level of annual cash flow while producing a very different total economic outcome over a longer holding period.
By itself, cash-on-cash return does not fully tell you the effect of future rent changes, major capital expenditures, principal reduction, appreciation or depreciation, sale proceeds, transaction costs, tax consequences, refinancing, the timing of cash flows over multiple years, or whether the underlying rent and expense assumptions are credible.
That does not make the metric weak. It means the metric should be used for the question it is designed to answer.
Cash-on-cash return is useful for understanding current pre-tax cash generation relative to investor cash. It is not a complete investment verdict and should not be treated as a substitute for a broader real estate deal analysis.
Common Cash-on-Cash Return Mistakes
Using gross rent instead of cash flow
Cash-on-cash return is not annual rent divided by the down payment. Gross rent ignores vacancy, operating expenses, and financing. Build the investor cash flow before calculating the percentage.
Using NOI without subtracting debt service
NOI is calculated before financing under the Realty Crafts convention. For a financed property, using NOI directly in the cash-on-cash numerator can materially overstate the cash actually available to the investor.
Using only the down payment as cash invested
If the investor also pays closing costs, points, immediate repairs, or other required acquisition cash, using only the down payment understates the denominator.
Mixing monthly cash flow with annual invested cash
Cash-on-cash return is commonly reported using a full year of pre-tax cash flow. If your model produces monthly cash-flow figures, add the 12 modeled months, including uneven vacancy, repairs, and other costs, before dividing by total cash invested. Multiplying a representative monthly average by 12 is appropriate only when it reasonably represents the full year. Do not label a one-month cash-flow ratio as an annual return.
Double counting taxes or insurance
A mortgage payment may be quoted as principal, interest, taxes, and insurance. If taxes and insurance have already been included as operating expenses above NOI, subtracting the entire combined payment again can count them twice.
Omitting normal operating expenses
A property can appear to have an excellent cash-on-cash return when maintenance, management, vacancy, utilities, or other normal costs are missing. A high return produced by incomplete underwriting is not a stronger investment metric.
Using inconsistent reserve conventions
If one calculation subtracts a replacement reserve below NOI and another does not, their cash-on-cash percentages are not directly comparable without recognizing the difference. State the reserve convention and apply it once.
Treating appreciation as current cash flow
An increase in estimated property value is not annual operating cash flow received by the investor. Keep appreciation separate from the current cash-on-cash calculation.
Assuming the highest cash-on-cash return is automatically best
A higher percentage can result from better property economics, less investor cash, more leverage, omitted expenses, or a combination of factors. Investigate why the result is higher before treating the number as evidence of a better deal.
Cash-on-Cash Return Checklist
Before relying on the result, verify that:
- rent and vacancy assumptions are supportable;
- normal operating expenses are included;
- NOI follows a clearly stated convention;
- debt service is subtracted without double counting taxes, insurance, or other escrowed expenses already modeled above NOI;
- separately modeled reserves or capital requirements are identified and applied once;
- total cash invested is complete and clearly defined;
- annual cash flow is compared with an invested-cash figure that uses the intended time period and convention;
- the arithmetic has been recalculated; and
- the final percentage is interpreted alongside property condition, financing, liquidity, market context, capital needs, and risk.
Frequently Asked Questions
Does cash-on-cash return include mortgage payments?
For a financed property, the calculation accounts for the mortgage through debt service in the numerator. For a standard fully amortizing mortgage, principal and interest are part of debt service. Other loan structures can produce different scheduled debt service, so use the financing terms actually being analyzed. Taxes or insurance should not be subtracted again below NOI if they are already included in operating expenses.
Does cash-on-cash return include closing costs?
Buyer-paid closing costs that are part of the investor’s actual acquisition cash are generally included in the cash-invested denominator under the acquisition-focused convention used in this guide. The key is to define the denominator clearly and apply the same convention when comparing properties.
Should lender-required reserves be included in total cash invested?
Not automatically. Cash to close and funds required to remain available after closing are different economic categories. If a lender-required reserve, restricted account, or retained-liquidity amount is included in the denominator, state that convention explicitly so the result can be compared consistently.
Is cash-on-cash return an annual measure?
It is commonly expressed using annual pre-tax cash flow and an invested-cash denominator. Keep the time basis consistent, and label a different measurement period if you use one.
Is cash-on-cash return the same as cap rate?
No. Cash-on-cash return compares annual pre-tax investor cash flow with investor cash invested and is sensitive to financing. Cap rate compares NOI with property price or value before investor financing under the Realty Crafts property-level convention.
Use Cash-on-Cash Return Inside a Complete Underwriting Process
Use the metric only after the inputs have been reconciled. Start with supportable income and operating expenses, calculate NOI, apply financing and any separately modeled below-NOI cash requirements, then compare the resulting annual pre-tax cash flow with the investor cash included in the denominator.
The result should answer one question clearly: how much current pre-tax cash flow the stated investment structure produces relative to the cash committed under the chosen convention. It should not be stretched into a total-return measure or a buy-or-reject decision by itself.
If you are evaluating a specific acquisition, return to Rental Property Analysis for the complete underwriting sequence. If the next question is how the property produces the dollar amount used in the numerator, continue with Rental Property Cash Flow.